IUL vs Whole Life for Infinite Banking| Legacy Life Planning
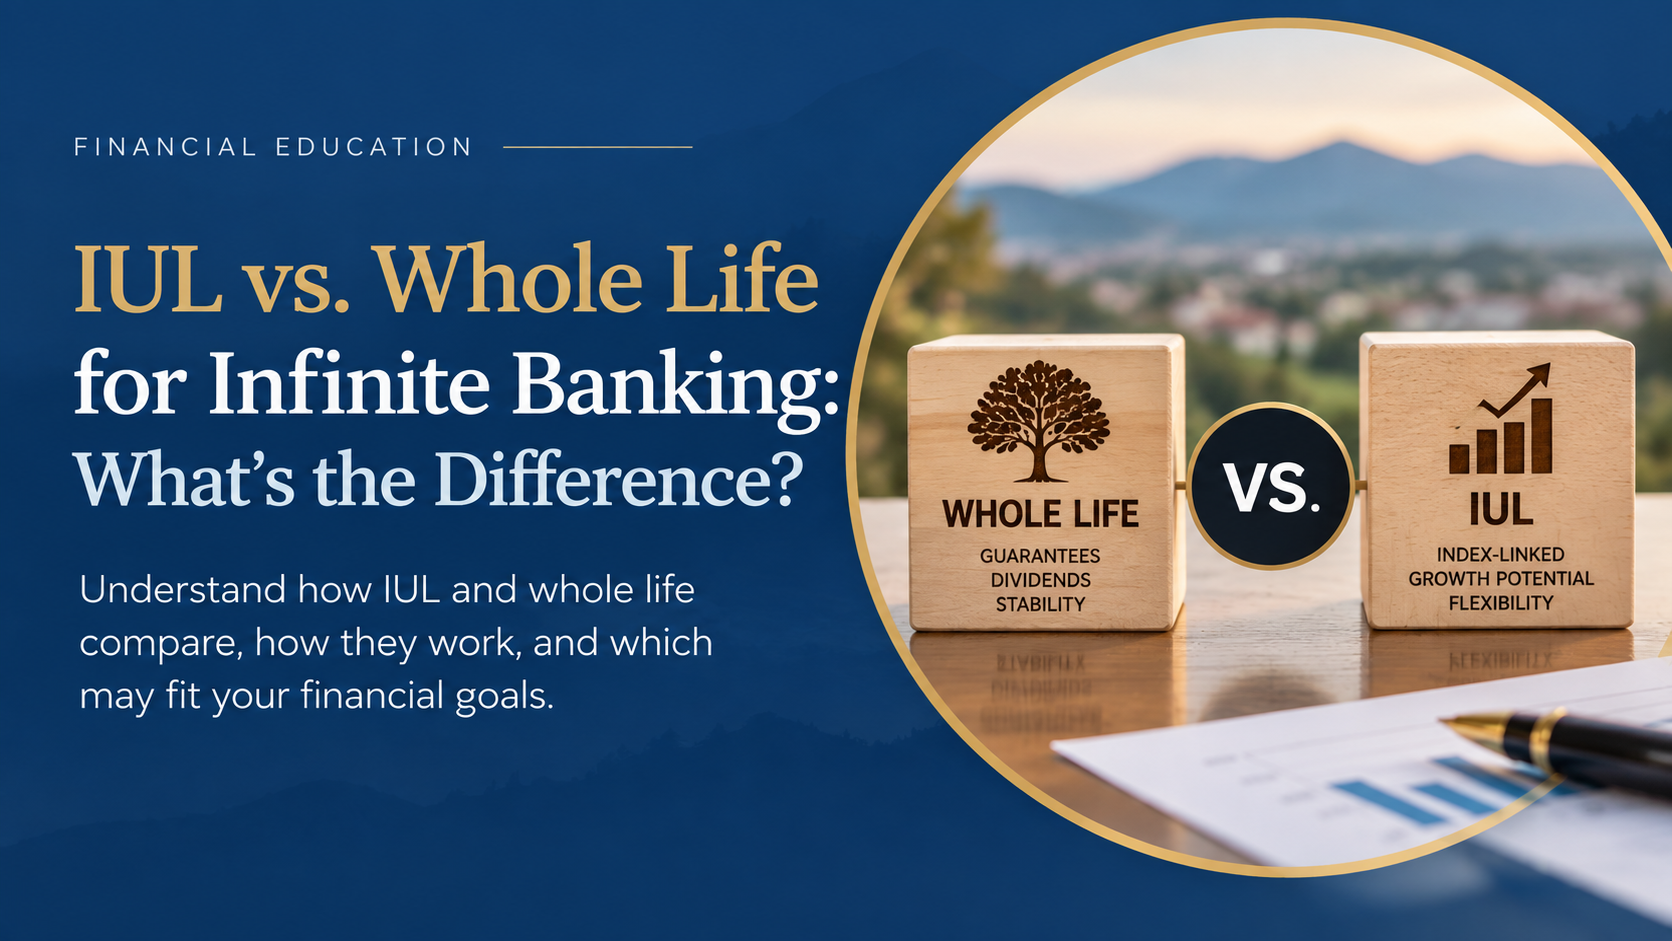
If you’ve been researching Infinite Banking, you’ve probably run into two types of permanent life insurance: whole life and Indexed Universal Life (IUL). Both build cash value, both provide permanent coverage, and both allow access to that value through policy loans. But they’re not the same strategy, and the distinction matters.
If you’re specifically interested in the Infinite Banking Concept® developed by Nelson Nash, participating whole life insurance is the traditional platform used to implement it. Indexed Universal Life is a different type of permanent life insurance, with different guarantees, costs, flexibility, and growth mechanics. That doesn’t make one product good and the other bad. It means the question worth asking isn’t “which one earns more,” it’s “what am I trying to accomplish, and which policy structure fits that goal.”
At Legacy Life Planning, we help individuals, families, and business owners in Johnson City and throughout the Tri-Cities work through those differences before deciding whether either strategy belongs in their financial plan.
Schedule a Free Strategy Session With Lance →
Infinite Banking gets used loosely online to describe almost any strategy involving cash-value life insurance and policy loans. That’s not how the term originated. The Infinite Banking Concept®, developed by Nelson Nash, is a financial process built around controlling more of your own financing instead of automatically relying on outside banks and lenders. The traditional platform for implementing it is a properly structured, dividend-paying participating whole life insurance policy.
The policy builds cash value over time, and that cash value can serve as collateral for loans from the insurance company. Instead of liquidating your accumulated asset every time you need money, you may be able to borrow against it and repay the loan according to your own strategy.
So Infinite Banking isn’t simply “buy life insurance and borrow from it.” The policy provides the financial platform. The broader concept is how you save, finance purchases, manage cash flow, repay loans, and think about capital over the long term.
Learn more about Infinite Banking & IUL Planning →
This is where most of the online confusion starts. An Indexed Universal Life policy can build cash value and offer policy loans, so some advisors use IUL in strategies that resemble parts of Infinite Banking. But in the specific Nelson Nash sense, IUL isn’t the policy type he prescribed. The Infinite Banking Concept traditionally uses participating whole life because of the contractual guarantees, predictable structure, and dividend potential available from properly designed policies.
IUL works differently. Its cash-value growth can be linked to the performance of an external market index, subject to policy provisions like caps, participation rates, spreads, floors, and charges. These are two different cash-value life insurance strategies, not two interchangeable ways of doing Infinite Banking.
Whole life is one of the oldest forms of permanent life insurance. A properly structured participating whole life policy generally includes a guaranteed death benefit, guaranteed cash-value accumulation according to the contract, level premiums, the potential for dividends from a participating insurer, access to cash value through policy loans, and permanent coverage when required premiums are paid.
Dividends aren’t guaranteed, but the underlying contractual guarantees don’t depend on stock-market performance. For Infinite Banking, policies are typically designed differently than an ordinary whole life policy bought mainly for death-benefit protection, the goal is usually to emphasize cash-value accumulation while still maintaining the life insurance structure the contract requires.
Why Whole Life Is Used for Infinite Banking
The strategy places a high value on predictability and control. When you’re building a pool of capital you may eventually use for vehicles, business expenses, real estate, equipment, or other opportunities, knowing how the underlying asset works matters. Whole life provides a relatively predictable foundation.
That doesn’t mean there are no costs or tradeoffs. Cash value usually takes time to build, particularly in the early years, and whole life requires a long-term commitment to properly fund the policy. But properly structured whole life emphasizes stability over maximizing projected returns.
IUL is also permanent life insurance, but it works differently. A policy generally includes a death benefit, cash-value accumulation, flexible premium features, interest crediting linked to one or more external market indexes, a minimum crediting floor, policy loans and withdrawals, and various charges and insurance costs.
Your cash value isn’t directly invested in the stock market. Instead, the insurance company uses a formula tied to an index to determine how much interest gets credited to the policy. For example, an IUL might reference the S&P 500. If the index rises, the policy may receive positive interest crediting according to its participation rate, cap, spread, or other crediting rules. If the index declines, the crediting rate may be protected by a floor.
A 0% index-crediting floor does not mean your total policy value can’t decline. Insurance charges and other policy expenses still apply, and that distinction matters.
Here’s the simplest comparison.
Both can work well when properly designed for the right person, but they solve somewhat different problems.
Need Personalized Advice for Your Family or Business?
Lance Evans provides tailored financial planning, tax reduction strategies, and estate security for East Tennessee residents.
Schedule a Strategy CallRecent Financial Articles
September 12, 2026
September 12, 2026
September 4, 2025
Ready to Take Control of Your Financial Legacy?
Schedule a 1-on-1 strategy session with Lance to review your tax exposure, retirement savings, or business funding options.